"In the 1980s my family was living in Jeddah, Saudi Arabia. During summer vacations we visited Larnaca in Cyprus a couple of times. What I remember from those trips is the UN blue-helmet soldiers stationed there, the beautiful Greek forum, and that unmistakable Mediterranean sea air. Nearly forty years later, Cyprus stands for considerably more than a childhood summer memory."
— Dr. Dieter Hovorka, PhDCyprus is a jurisdiction that rewards those who take the time to understand it properly. On the surface it looks like a small Mediterranean island with a complicated history. Look closer and you find an EU member state with a competitive 15% corporate tax rate, an IP Box that reduces the effective rate on qualifying intellectual property income to approximately 2.5%, a Non-Dom regime that gives internationally mobile individuals up to 17 years of zero tax on dividend and interest income, a 60-day residency rule that requires only a modest physical presence to anchor tax residency, and the largest ship management centre in the European Union. In 2026, following the most comprehensive tax reform Cyprus has seen in two decades, it remains one of the most structurally attractive jurisdictions in Europe for entrepreneurs, investors, holding companies, technology businesses, and shipping operators.
This is not a theoretical guide. The clients I work with at 1Stop Connect and its accredited program partner who use Cyprus structures include holding company groups that benefit from the combination of EU membership and competitive corporate tax, technology founders who use the IP Box for royalty and licensing income, and internationally mobile individuals who have established Cyprus tax residency under the 60-day rule. Each of these groups uses Cyprus differently, and each encounters different considerations. This article covers all three angles.
- Why Cyprus in 2026 — What Has Changed and What Has Not
- Corporate Tax: 15%, the IP Box, and Key Exemptions
- The Non-Dom Regime: 17 Years of Zero Dividend Tax
- The 60-Day Residency Rule — How Little Presence Is Enough
- Cyprus as a Holding Company Jurisdiction
- Cyprus Shipping: Tonnage Tax, Registry and the EU's Largest Ship Management Centre
- Cyprus vs UAE vs Ireland: A Quick Comparison
- Frequently Asked Questions
Why Cyprus in 2026 — What Has Changed and What Has Not
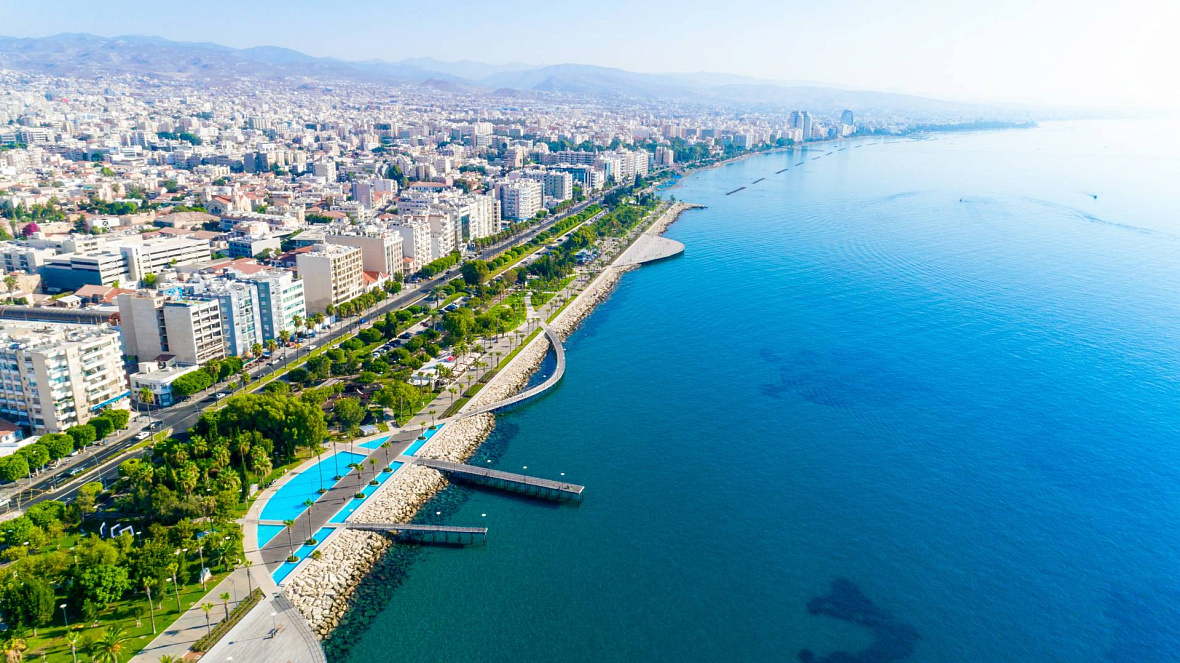
Limassol is the commercial heart of Cyprus, home to over 50 international shipping companies and a growing fintech and technology cluster.
The headline news from Cyprus in 2026 is the tax reform that came into force on 1 January 2026. The reform, approved by Parliament on 22 December 2025, raised the corporate income tax rate from 12.5% to 15% in line with the OECD Pillar Two global minimum tax requirements. For those who have been following Cyprus for years, the headline feels significant. In practice, the impact is more nuanced than it first appears.
What changed: the headline corporate tax rate, the special defence contribution on dividends (reduced from 17% to 5% for post-2026 profits distributed to qualifying recipients), the deemed dividend distribution mechanism (abolished for post-2026 profits), the loss carry-forward period (extended from 5 years to up to 10 years under certain conditions), the R&D super-deduction (extended through 2030 at 120% of qualifying costs), and the personal tax-free threshold (raised from €19,500 to €22,000).
What did not change: the IP Box regime, the Non-Dom exemption from SDC on dividends and interest, the 0% withholding tax on dividends paid to non-Cyprus residents, the 60-day residency rule, the tonnage tax scheme for shipping, the 0% capital gains tax on disposal of securities, and the 0% inheritance tax. KPMG's analysis of the reform confirms that the competitive foundations of the Cyprus tax framework remain largely intact despite the rate increase.
Corporate Tax: 15%, the IP Box, and Key Exemptions
The Cyprus IP Box reduces the effective rate on qualifying IP income to approximately 2.5%, the lowest in the EU and fully OECD BEPS compliant.
The standard Cyprus corporate income tax rate is 15% from 1 January 2026. All Cyprus tax-resident companies pay this rate on their worldwide taxable profits after allowable deductions. Companies incorporated in Cyprus are treated as Cyprus tax-resident unless their management and control is exercised elsewhere. Companies incorporated abroad but managed and controlled from Cyprus may also be treated as Cyprus tax-resident.
The most significant tax advantage for technology, software, pharmaceutical, and licensing businesses is the IP Box. The Cyprus IP Box provides an 80% deduction from the taxable income base on qualifying intellectual property income, including software royalties, patent licensing fees, and income from qualifying IP that the Cyprus entity has developed or contributed to developing. At 15% CIT on the remaining 20% of qualifying income, the effective gross rate is 3%, approximately 2.5% on net IP profit after the standard 80% deduction. The regime uses the OECD BEPS nexus approach, requiring genuine connection between the IP development activity and the Cyprus entity, and is fully compliant with EU state aid rules.
Beyond the IP Box, several key income categories remain exempt from Cyprus corporate income tax entirely. Dividend income received by a Cyprus company from another company is exempt from CIT, subject to anti-abuse conditions. Capital gains from the disposal of securities (shares, bonds, debentures, and other financial instruments) are fully exempt from CIT and capital gains tax, provided the underlying assets do not consist principally of immovable property in Cyprus. Profits from foreign permanent establishments are generally exempt, subject to the EU non-cooperative jurisdiction blacklist provisions. And for shipping companies, profits from the operation, charter, or management of qualifying vessels are fully exempt from CIT and are instead subject to the tonnage tax scheme at fixed annual rates by vessel tonnage.
The Non-Dom Regime: 17 Years of Zero Dividend Tax
Cyprus Non-Dom status gives up to 17 years of zero dividend and interest tax within the EU. The 2026 reform made dual residency possible.
The Cyprus Non-Domiciled tax regime is one of the most compelling in Europe for internationally mobile individuals who receive dividend and investment income. A Cyprus Non-Dom is a Cyprus tax resident who is not considered domiciled in Cyprus for Special Defence Contribution (SDC) purposes. The SDC is the tax that would otherwise apply to dividends and interest for Cyprus-domiciled tax residents. Non-doms are fully exempt from it.
In practice this means: non-dom individuals are exempt from SDC on dividends and interest received from anywhere in the world for up to 17 years from the date they first become Cyprus tax residents. Dividends from a Cyprus company, dividends from a UAE company, dividends from a BVI holding structure, all received free of SDC for 17 years. The only additional charge that may apply is the General Healthcare System contribution at 2.65% of dividend income, subject to the statutory annual ceiling.
After 17 years, non-dom status expires unless the individual pays a €250,000 lump sum to extend it for a further five-year period, with a second extension available at the same cost. This change was introduced in the 2026 reform and provides long-term planning flexibility for those who intend to remain in Cyprus beyond the initial 17-year window.
What non-dom status does not cover: employment income, self-employment income, rental income from Cyprus property, and professional income remain taxable under standard income tax rates at progressive rates from 0% on the first €22,000 (raised from €19,500 in the 2026 reform) up to 35% on income above €60,000. For individuals who structure correctly — drawing minimal salary and receiving most of their economic return through dividends from a Cyprus company: the effective personal tax position can be very competitive. 1Stop Connect and its accredited partner advises on the interaction between company structure and personal tax position for clients considering Cyprus residency.
Before the 2026 reform, qualifying for Cyprus tax residency under the 60-day rule required the individual not to be tax resident in any other country during the same tax year. This condition has been removed effective 1 January 2026. Dual tax residency is now explicitly permitted. Where a dual residency situation arises, it is resolved through the tie-breaker rules of the applicable double tax treaty between Cyprus and the other country. This makes Cyprus significantly more accessible for entrepreneurs and investors who maintain business or family connections in other countries and cannot easily sever their previous tax residency.
The 60-Day Residency Rule — How Little Presence Is Enough
Cyprus offers two routes to tax residency for individuals. The standard route is 183 days per year of physical presence in Cyprus. The more relevant route for internationally mobile founders and investors is the 60-day rule.
Under the 60-day rule, an individual becomes a Cyprus tax resident in a calendar year if they meet all of the following conditions: they spend at least 60 days in Cyprus during that year; they maintain a permanent residence in Cyprus (owned or rented); they carry on a business in Cyprus, are employed in Cyprus, or hold a directorship in a Cyprus tax-resident company; and they do not spend more than 183 days in any single other country during that year.
Since the 2026 reform removed the requirement to be non-resident elsewhere, these four conditions are now the complete test. An entrepreneur who lives primarily in Dubai, maintains a Cyprus apartment, holds a directorship in a Cyprus company, spends 65 days per year in Cyprus, and travels extensively across multiple countries can now qualify as a Cyprus tax resident and access Non-Dom status without giving up UAE residency. The interaction between UAE and Cyprus tax residency for individuals depends on the applicable double tax treaty, which Cyprus and the UAE signed and which has been in force since 1998.
Cyprus as a Holding Company Jurisdiction
Cyprus holding companies benefit from 0% withholding on outbound dividends, full participation exemption, and 0% capital gains on share disposals.
Cyprus has been a preferred holding company jurisdiction for European and international groups for over two decades. The combination of EU membership, an extensive double tax treaty network (over 60 treaties), 0% withholding tax on dividends paid to non-Cyprus resident shareholders, full participation exemption on dividends received from subsidiaries, and 0% capital gains tax on disposal of securities makes it a structurally efficient holding location.
A Cyprus holding company receiving dividends from operating subsidiaries in Germany, Romania, or the UAE pays no Cyprus corporate income tax on those dividends (participation exemption applies). When it distributes those dividends to its own shareholders outside Cyprus, no withholding tax applies at the Cyprus level. When it eventually sells a subsidiary, the gain is fully exempt from Cyprus capital gains tax and CIT. The EU Parent-Subsidiary Directive eliminates withholding on dividends flowing upward from EU subsidiaries to the Cyprus holding company. This combination is difficult to replicate in most other EU jurisdictions at a 15% CIT rate.
Substance requirements have tightened across the board. A Cyprus holding company that exists only on paper, with no real management decisions made in Cyprus and no genuine directors exercising control from the island, is increasingly likely to be challenged by foreign tax authorities applying controlled foreign company rules or anti-avoidance measures. Genuine Cyprus holding structures require Cyprus-resident directors with real decision-making authority, board meetings held in Cyprus, and the management and control of the company being genuinely exercised on the island. 1Stop Connect and its accredited partner can assist with the full substance package for Cyprus holding company clients, including directorship services, registered office, and compliance support.
Cyprus Shipping: Tonnage Tax, Registry and the EU's Largest Ship Management Centre
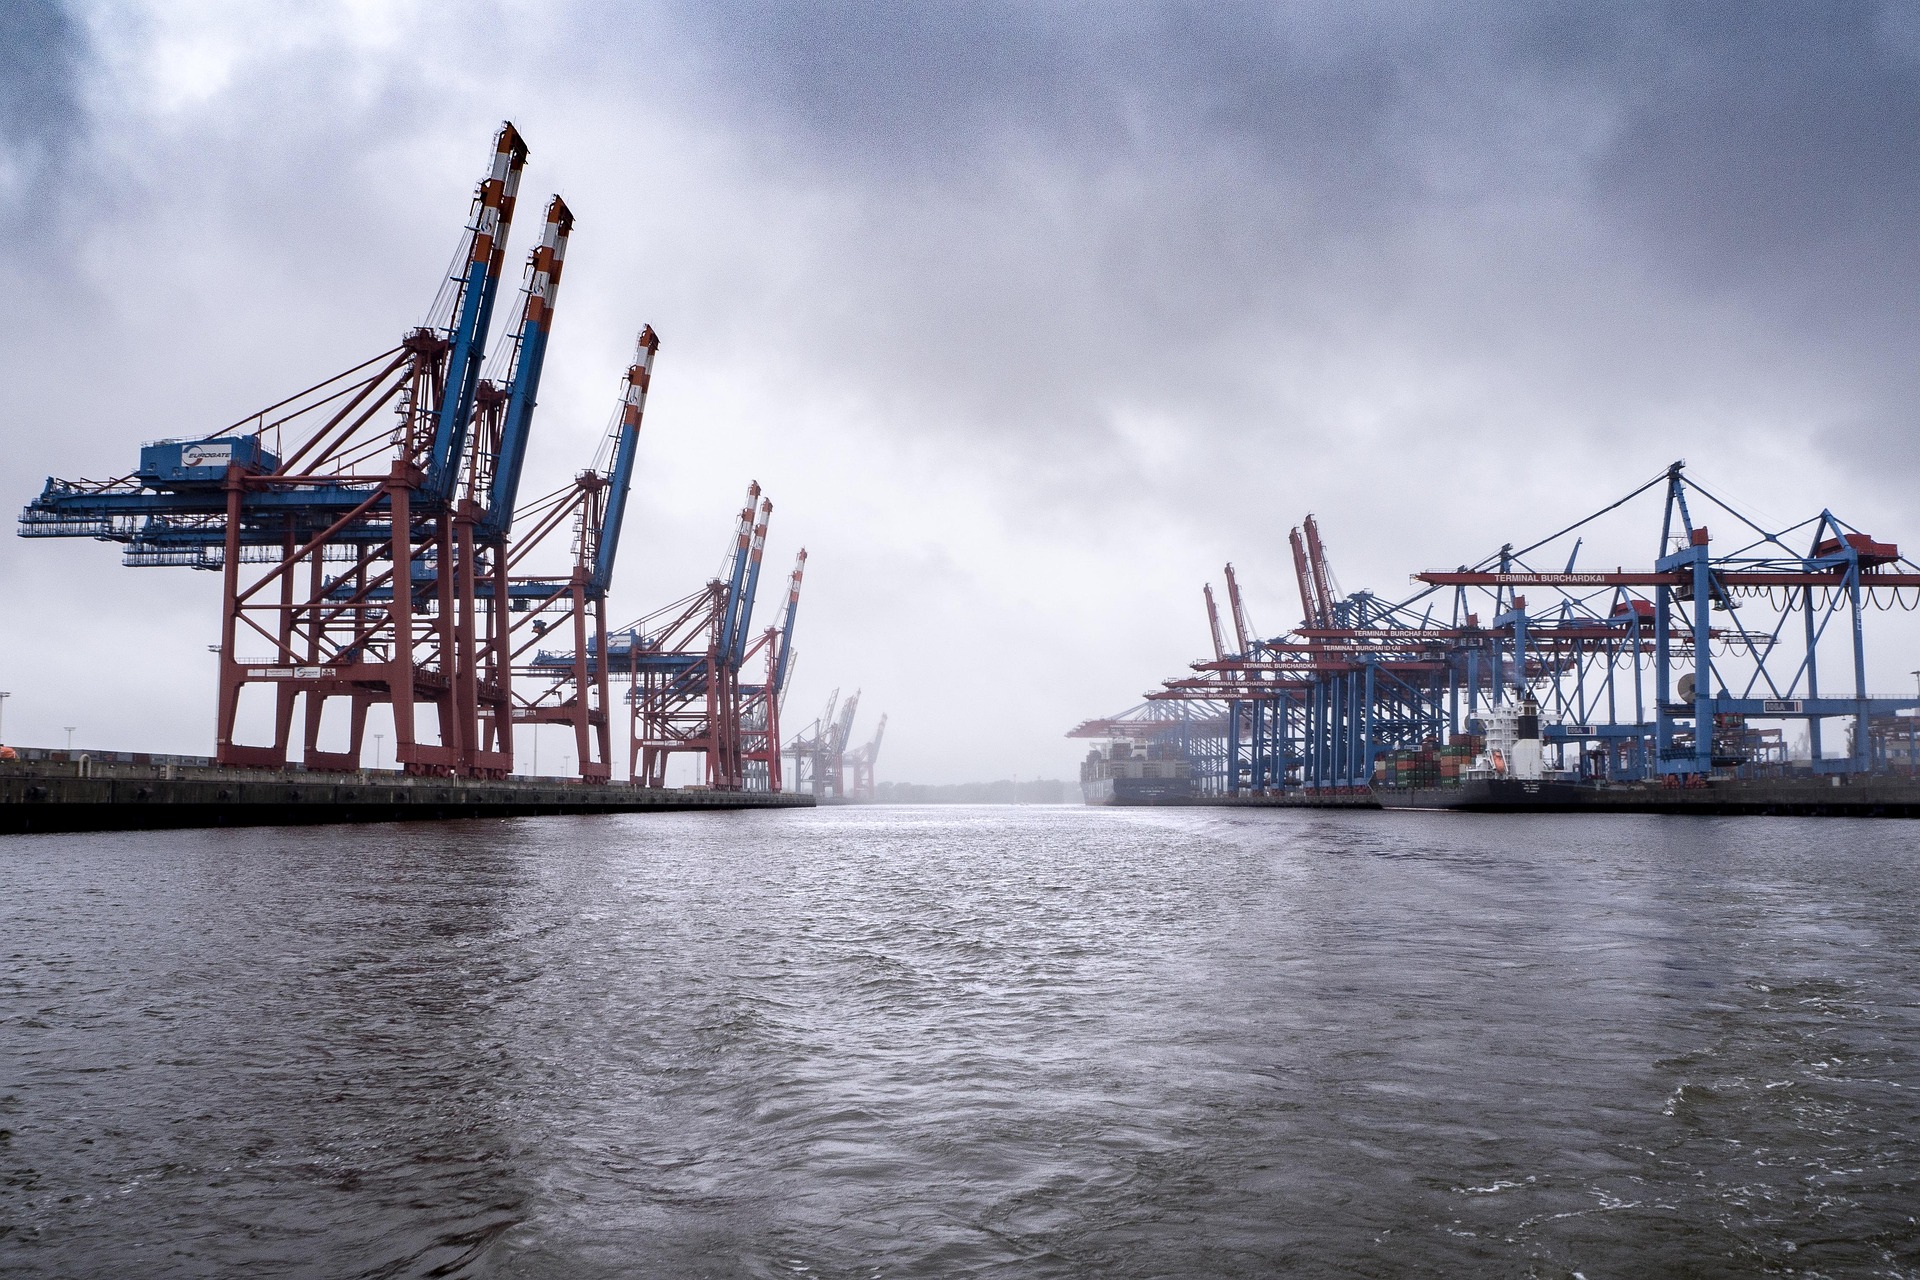
Limassol port anchors the EU's largest ship management centre. Registry tonnage is up 23% since 2023, its highest level in 25 years.
Cyprus occupies a unique position in global shipping that goes beyond its function as a tax jurisdiction. It is the largest ship management centre in the European Union, hosting over 50 international shipping companies in Limassol that together manage a substantial proportion of global shipping tonnage. The infrastructure, legal framework, talent base, and regulatory environment that this concentration of shipping expertise provides is genuinely difficult to replicate elsewhere in the EU.
The legal foundation of Cyprus's shipping attraction is the tonnage tax scheme. Profits derived by the owner of a qualifying ship from its operation or charter are fully exempt from all direct taxes, including corporate income tax. Instead, qualifying ship-owning companies pay an annual tonnage tax calculated at fixed rates based on the net tonnage of their vessels: a small, predictable, operationally irrelevant cost compared to the profits that would otherwise be taxable. The scheme applies to vessels registered in the EU/EEA and, under certain conditions, vessels registered in other approved jurisdictions.
The 2026 shipping reforms added meaningful enhancements to an already strong framework. A dedicated shipping Registrar was introduced, allowing eligible companies to transfer into a specialist registry structure. Stamp duty was abolished for the sector. The social cohesion levy for non-resident seafarers was removed. And environmental incentive reductions, available to owners adopting qualifying emission-reduction measures, were updated and extended. Registry gross tonnage has grown 23% since September 2023, reaching its highest level in approximately 25 years: a clear signal that the shipping community is voting with its registrations.
For ship owners and managers considering their registry and management structure, Cyprus offers the rare combination of EU-flag access (with the commercial and regulatory advantages that brings), a fully exempt profit position under the tonnage tax scheme, and an operational ecosystem of brokers, lawyers, seafarer supply companies, and technical managers that no other EU jurisdiction can match at scale.
Cyprus vs UAE vs Ireland: A Quick Comparison
| Feature | Cyprus 2026 | UAE | Ireland |
|---|---|---|---|
| Corporate tax rate | 15% | 0% / 9% (over AED 375k) | 12.5% trading |
| IP / tech income | ~2.5% effective (IP Box) | 0% qualifying free zone | 6.25% (KDB) |
| Dividend withholding | 0% to non-residents | 0% | 20% (treaty reduced) |
| Capital gains on shares | 0% | 0% | 33% CGT |
| Inheritance tax | 0% | 0% | 33% CAT |
| Individual dividend tax | 0% (Non-Dom, 17 years) | 0% (personal income) | Up to 52% USC + PRSI |
| EU membership | Yes — full single market | No | Yes — full single market |
| Residency requirement | 60 days per year | 183 days (or employment) | 183 days |
| Shipping / tonnage tax | Yes — EU's largest centre | Limited | Tonnage tax available |
| Treaty network | 65+ treaties | 140+ treaties | 75+ treaties |
The table makes a point that is worth stating directly: Cyprus does not win on every dimension. The UAE offers a lower corporate tax rate and zero personal income tax without any SDC considerations, and it remains the stronger choice for business owners who are or plan to be UAE resident. Ireland offers deeper integration with EU trading relationships for businesses with significant EU sales and operations. What Cyprus offers is the specific combination of EU membership, the lowest effective IP income tax rate in the EU, zero dividend tax for non-doms, zero capital gains on securities, zero inheritance tax, a 60-day residency rule, and world-class shipping infrastructure, all within a single jurisdiction, within the EU legal framework. That combination is genuinely unique.
For the right client profile: an internationally mobile entrepreneur or investor who wants EU membership, genuinely competitive IP tax, personal dividend exemption, and a Mediterranean lifestyle with relatively light physical presence requirements: Cyprus in 2026 is difficult to better within the EU. Contact 1Stop Connect and its accredited program partner to discuss how a Cyprus structure fits your specific situation, including the interaction with any existing UAE, Nevis, or Seychelles entities you may already have in place.
"The 2026 reform raised the headline rate but left the structure intact. Cyprus remains the only EU jurisdiction where you can combine a 2.5% effective IP tax rate, zero dividend tax as an individual, zero capital gains on securities, zero inheritance tax, and residency on 60 days a year."
— Dr. Dieter Hovorka, PhDFrequently Asked Questions
What is the Cyprus corporate tax rate in 2026? +
15% from 1 January 2026, up from 12.5%, aligned with the OECD Pillar Two global minimum tax. The IP Box reduces the effective rate on qualifying IP income to approximately 2.5%. Shipping profits under the tonnage tax scheme are fully exempt from CIT.
What is Cyprus Non-Dom status and who qualifies? +
Non-Dom status gives Cyprus tax residents who are not Cypriot-domiciled a 17-year exemption from the Special Defence Contribution on dividend and interest income. This means zero tax on dividends and interest received from anywhere in the world. Qualification requires Cyprus tax residency (183-day or 60-day rule), no Cypriot domicile of origin, and fewer than 17 years of Cyprus tax residency in the previous 20 years. 1Stop Connect and its accredited partner can advise on the full qualification process.
How does the Cyprus 60-day residency rule work? +
Spend at least 60 days in Cyprus per year, maintain a permanent Cyprus residence, hold a directorship or employment in a Cyprus company, and do not spend more than 183 days in any single other country. Since the 2026 reform, dual residency is now permitted. The previous requirement to be non-resident elsewhere has been removed.
What is the Cyprus IP Box regime? +
An 80% deduction from the taxable income base on qualifying IP income: software royalties, patent licensing, and income from IP developed by the Cyprus entity. At 15% CIT this produces a gross effective rate of approximately 3%, or 2.5% on net profit. The regime is OECD BEPS Action 5 compliant. The 120% R&D super-deduction has been extended through 2030.
Why is Cyprus a leading shipping jurisdiction? +
Cyprus is the EU's largest ship management centre, with over 50 international companies in Limassol. The tonnage tax scheme provides full CIT exemption on ship operation profits, with a small fixed annual tonnage tax replacing income tax. The 2026 reforms added a dedicated shipping Registrar, abolished stamp duty, and removed the social cohesion levy for non-resident seafarers. Registry gross tonnage has grown 23% since September 2023.
How does Cyprus compare to the UAE for an internationally mobile entrepreneur? +
The UAE offers a lower corporate tax rate and zero personal income tax for UAE residents, and is the stronger choice for entrepreneurs who are or plan to be UAE-based. Cyprus offers EU membership, the 2.5% IP Box, zero dividend tax as a non-dom individual, zero capital gains on securities, zero inheritance tax, and residency on just 60 days per year, within the EU legal framework. For clients who already have UAE or offshore structures, Cyprus can sit effectively above or alongside those structures. See also our article on beneficial ownership registers for context on how Cyprus fits into a broader international structure.